Dados necessários para melhorar nosso serviço e personalizar a sua experiência.
The Supreme Court defines the modulation of the effects of the decision that ruled to exclude ICMS from the PIS and Cofins calculation base
Supreme defines the modulation of the effects of the decision that understood the exclusion of ICMS from the PIS and Cofins calculation base
RE 574.706/PR; Topic of General Repercussion No. 69
The Federal Supreme Court (STF) finalized the judgment last Thursday, May 13th, of the motions for declaration against the decision given in an Extraordinary Appeal that defined the exclusion of ICMS from the PIS and Cofins calculation base. The appeal in question aimed to discuss whether the effects of the decision defining the exclusion of the tax from the calculation base would be valid or not from the date on which it was issued, which is March 15, 2017. Another point discussed in the appeal is the definition of which ICMS should be removed from the contribution calculation base: the one actually paid or the one highlighted in the invoice.
The Rapporteur of the case, Minister Cármen Lúcia, discussed in her vote that the Court had been making decisions in favor of excluding the ICMS from the aforementioned calculation base since 2014, but following a different composition and without general repercussions. For this reason, it would be of great importance to modulate the effects of the decision to maintain legal certainty. The understanding was followed by the majority of Ministers, on a score of 8 to 3, with a forward modulation being opted, without retroactive effects. Regarding the definition of which ICMS should be removed from the contribution base, the Court understood that it should be the one highlighted in the invoice. Finally, it was defined that only judicial and administrative actions filed up to the trial date in 2017 would be exempt.
Regarding the modulation of effects, Ministers Edson Fachin, Rosa Weber and Marco Aurélio were defeated. Regarding the definition of which ICMS should be removed from the calculation base, Ministers Nunes Marques, Luis Roberto Barroso and Gilmar Mendes were defeated.
STF decides to validate the Difal charge for Simples Nacional companies.
RE 970.821/RS
The Federal Supreme Court (STF) ruled on the constitutionality of charging the ICMS rate differential (Difal) by companies that are part of Simples Nacional on interstate purchases. In the action, it is clear that the Difal charge can be made by the state in which the buyer of the goods is located, taking into account the difference between the interstate rates, related to the state in which the seller is located, and the internal state rate.
The majority of Ministers followed the vote of the Rapporteur, Minister Edson Fachin. The majority understanding of the Court addresses the constitutionality of the Difal charged by the state of destination upon the entry of goods into its territory when an acquisition is made by the company opting for Simples Nacional. The Minister Rapporteur also stated that adherence to Simples is optional, with the burden and bonuses arising from the choice made falling on the taxpayer.
On the occasion, the Minister Rapporteur proposed the thesis “the tax imposition of ICMS rate differential by the State of destination on the entry of goods into its territory owed by a business company adhering to Simples Nacional is constitutional, regardless of its position in the production chain or the possibility of offsetting credits”.
The divergence was with Ministers Alexandre de Moraes, Gilmar Mendes, Luis Roberto Barroso and Cármen Lúcia.
RE 970.821/RS
STJ decides to charge IRPJ and CSLL on investment gains
REsp 1,660,363 (AgInt)
The 1st Panel of the Superior Court of Justice (STJ) decided to maintain the understanding that it is possible for the government to charge Income Tax (IRPJ) and Social Contribution on Net Profit (CSLL) on the portion corresponding to monetary correction on gains arising from financial investments. The trial score was 3 to 2 due to the collection of taxes.
The vote given by the Rapporteur of the case, the then Minister Nunes Maia Filho, was that the charge would be undue as the monetary update was a mere recomposition of purchasing power. The other Ministers differed from their understanding by stating that it is necessary to maintain what had already been decided by the Court, which allowed taxation on income from financial investments and on the portion referring to monetary correction as it is an addition to assets.
It is noteworthy here that the Federal Supreme Court (STF), in the judgment of General Repercussion Issue No. 1,018, had already decided that the matter is infraconstitutional, and it is therefore up to the STJ to resolve the conflict.
STF decides that public companies and non-profit mixed capital companies have reciprocal tax immunity
RE 1320054; Topic of General Repercussion No. 1,140
The Federal Supreme Court (STF) reaffirmed its understanding on reciprocal tax immunity for public companies and mixed-capital companies delegating essential public services, regardless of charging a fee as consideration for the service. The case was decided unanimously by the Court.
The appellant requested the non-granting of tax benefits to public companies and mixed capital companies on the grounds that there is a constitutional provision (article 173, §§ 1 and 2) of entities that have immunity, which do not include the aforementioned state bodies. It also stated that the company in question makes a profit and does not receive budgetary resources to maintain its activities, in addition to charging fees to users.
At first, the President of the STF and Rapporteur of the case, Minister Luiz Fux, claimed that it was necessary to submit the matter to the general repercussion system in order to reaffirm the Court's dominant jurisprudence. Regarding the merits, the Rapporteur stated that a mixed capital company whose purpose is to operate an essential public service of public passenger transport upon payment of a fare, which confers the right to reciprocal immunity, an understanding supported by the other members of the Court.
At the time, the following thesis of general repercussion was defined: “Public companies and mixed-capital companies delegating essential public services, which do not distribute profits to private shareholders nor pose a risk to competitive balance, are beneficiaries of the reciprocal tax immunity provided for in article 150, VI, ‘a’, of the Federal Constitution, regardless of charging a fee as consideration for the service”.
RE 1320054
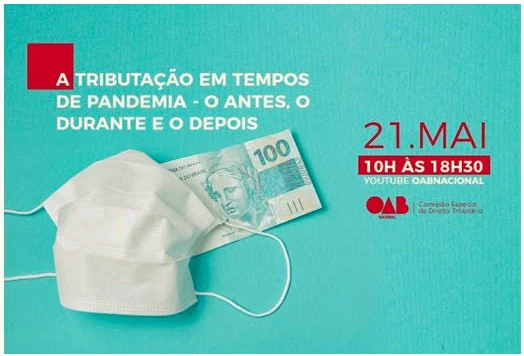
Debate promoted by the OAB will mark the launch of the book “Taxation in Times of Pandemic”
The Federal Council of the Brazilian Bar Association (OAB), through the Special Commission on Tax Law, will promote on May 21st, from 10am to 6:30pm, a virtual event to debate “Relevant Tax Judgments in Times of Pandemic”.
On the occasion, the book “Taxation in Times of Pandemic – The before, during and after” will be launched, organized by Eduardo Maneira (president of the Special Commission on Tax Law of the OAB), Kellen Crystian do Vale (vice-president of the Special Commission on Tax Law), Carlos Yury (Araújo de Morais – Sociedade de Advogados), Raquel Preto (Preto Advogados), Carlos Sant’Anna (Member of the Special Commission on Tax Law) and Felipe Crisanto (Consultant Member of the Special Commission on Tax Law).
The debate, on 21/5, will be opened by Eduardo Maneira and will feature the participation of some of the main names in Brazilian tax law. The event will discuss topics such as the modulation parameters adopted by the Federal Supreme Court in tax matters; the casting vote in the federal tax administrative process; the federal contribution on the constitutional third of vacation; and the issue of the incidence of ICMS in the PIS and Cofins calculation base.
Click here to check the full event schedule.
See other related news stories
Newsletters
Law 14,451/2022 – Reduction of legal quorums for limited companies
September 23, 2022Published on September 22, 2022, Law No. 14,451 of 2022, modifies articles 1,061 and 1,076 of the Civil Code and had as its main objective the reduction of legal quorums for the approval of corporate resolutions in Limited Companies. As soon...
Newsletters
SANCTIONED LAW THAT WILL UNIFY THE DATABASES OF ALL NOTARY OFFICES
July 14, 2022New law will allow legal acts and transactions to be registered and consulted electronically On June 28, 2022, Law no. 14,382/22 (result of the conversion into law of Provisional Measure nº 1,085/2021), which establishes the Electronic System of Public Records –...
Newsletters
Census of Foreign Capital in the Country
July 14, 2022On July 1, 2022, the Central Bank of Brazil – BACEN began receiving the Annual Census of Foreign Capital in the Country (“Annual Census”), observing the parameters of BACEN Circular No. 3,795/2016. The Annual Census is mandatory in relation to the...
Newsletters
Ordinary General Meetings to Approval the Financial Statements Corresponding to the 2021 Financial Year.
April 14, 2022The deadline for holding ordinary general meetings (AGM) for the fiscal year ending on December 31, 2021 ends on April 30, 2022, with the purpose of taking the administrators' accounts, as well as approving the financial statements and allocation of...
Newsletters
Program comes into force that exempts the events sector to combat the crisis caused by the pandemic
April 12, 2022On March 18, an extra edition of the Official Gazette of the Union (DOU) published the promulgation of the vetoed parts of Law No. 14,148/2021, which established the Emergency Program for the Resumption of the Events Sector – PERSE, essential...
Newsletters
BACEN: Deadline for submitting the Annual Declaration of Brazilian Capital Abroad is April 5th
February 25, 2022The deadline for submitting the Annual Declaration of Brazilian Capital Abroad (“CBE”) began on February 15, 2022, referring to the base date of December 31, 2021. Individuals or legal entities resident, domiciled or headquartered in the country, holding values of any...