Dados necessários para melhorar nosso serviço e personalizar a sua experiência.
Income tax reform and repeal of JCP: Brazil going against Europe
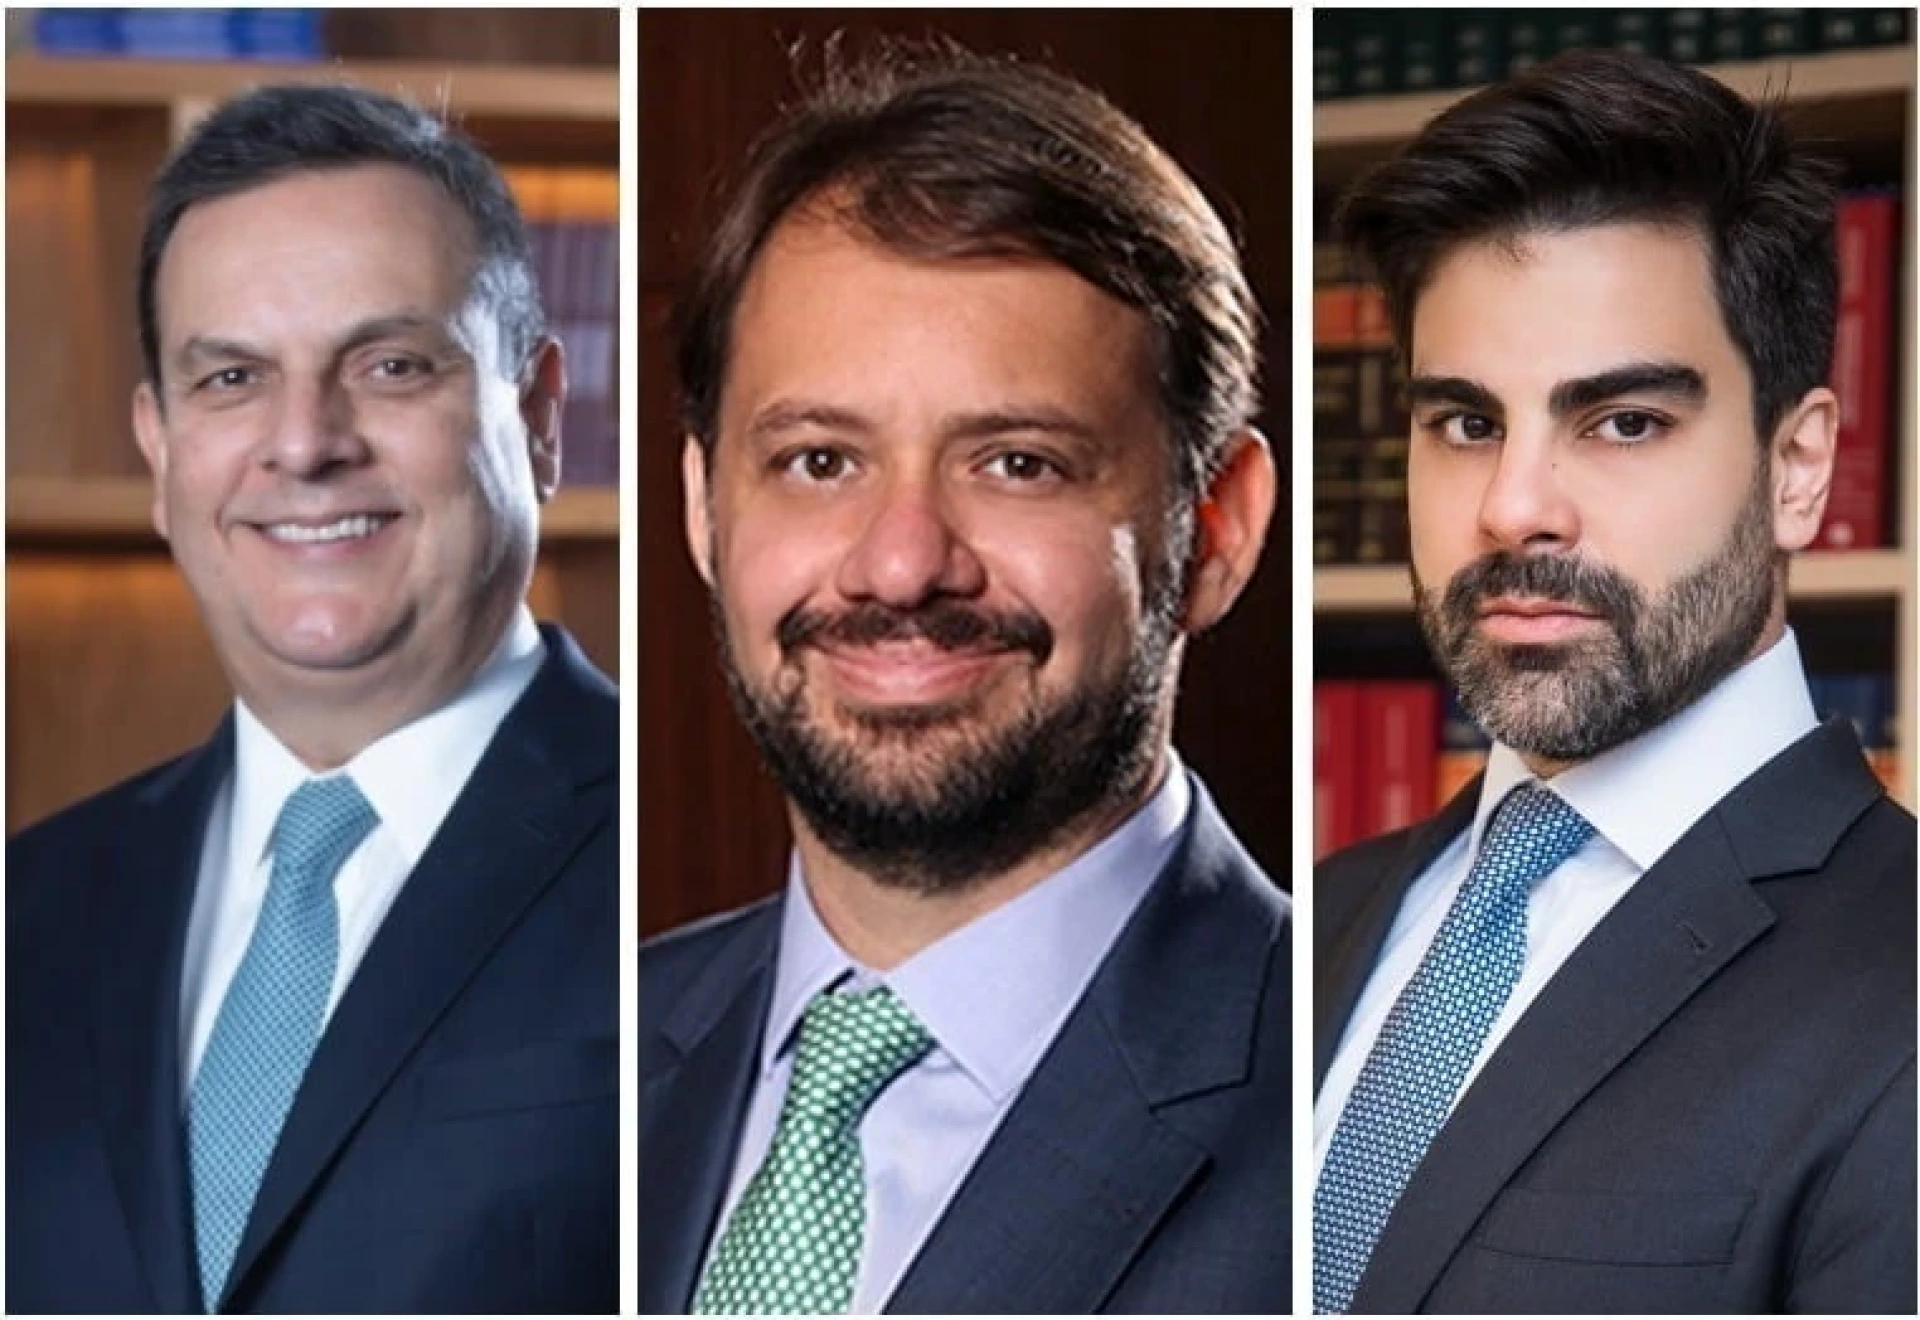
In an article published on the JOTA website, Drs. Eduardo Maneira, Donovan Mazza Lessa and Roberto Codorniz, partners at Maneira Advogados, analyze the income tax reform and the repeal of JCP (Interest on Own Capital).
Income tax reform and repeal of JCP: Brazil going against Europe
Rules from European countries and a new EU proposal also aim to limit debt bias arising from income taxation
EDUARDO MANEIRA
DONOVAN MAZZA LESSA
ROBERTO CODORNIZ LEITE PEREIRA
04/09/2023 13:51Updated on 04/09/2023 at 16:58
In the context of discussions regarding the reform of income taxation, Interest on Own Capital (JCP) has been highlighted as a “privilege” – or even a “tax benefit” – devoid of any justification, other than to privilege a select group of companies and investors.
From a tax point of view, JCP, paid to partners and shareholders of companies, represent a deductible expense in determining the calculation basis for corporate income tax (IRPJ) and social contribution on net profit (CSLL) owed by the company.
JCP are calculated based on the application of the long-term interest rate (TJLP) on the equity accounts, listed by article 9 of law 9,249/1995, as long as the limits provided for by the same provision are observed.
Being a mere “tax benefit”, the solution to increasing revenue would be simple: repeal the JCP. And it was exactly in this sense that the federal government sent bill (PL) 4,258/23 to the National Congress, to end its deductibility from 2024.
However, far from the emotions of the heated political debate, a serious and technical analysis of the JCP reveals that the institute fulfills an important function in the Brazilian tax system: reducing the bias that favors the indebtedness of Brazilian companies.
This bias is not a problem exclusive to the Brazilian tax system. In fact, all systems that tax business income deal with a natural incentive that exists in favor of business investment through costly capital (loans) when compared to investment in equity (contribution of partner resources in the form of an increase in share capital). In the first case, the investor becomes a mere creditor; in the second, an effective partner of the investee company.
From the corporate tax perspective, interest (i.e., the remuneration owed to the investor-creditor) is an operational expense that is deductible when calculating the IRPJ and CSLL calculation bases. In total, the effect of the deduction in terms of reducing taxes due corresponds to 34% (combined IRPJ and CSLL rate) of the value of interest paid.
For the investor, interest offers the opportunity to earn periodic and certain remuneration on the capital invested, which does not depend on corporate deliberation and is not conditioned on the success of the venture.
On the other hand, the dividends or profits distributed (the remuneration due to the investing partner) do not provide a similar advantage to the invested company, given that the aforementioned income is not an operational expense, and, therefore, cannot be deducted when calculating the IRPJ and CSLL calculation basis.
Furthermore, from a business perspective, the investor who contributes resources to the company in the form of a contribution to the share capital, like any other partner, incurs all the risks inherent to the business, so he cannot count on a certain and periodic remuneration on the amounts invested.
Congress sought to correct the pro-debt bias resulting from this distinction in tax treatments between interest and dividends in 1995, through two measures: exemption from dividends, concentrating taxation on legal entities at a rate (34%) higher than the average of other countries; profits distributed by Brazilian companies and the possibility of deducting JCP.
Therefore, it is clear that JCPs do not represent an odious tax benefit designed to increase the profitability of Brazilian companies and investors, but, on the contrary, they are an important instrument to reduce tax asymmetries that end up favoring corporate financing through third-party capital (in the form of debt) to the detriment of equity.
Furthermore, far from being a “Brazilian jabuticaba” invented and adopted exclusively in Brazilian lands, the concern with instruments to neutralize the investor's opportunity cost has been discussed in other countries.
Mechanism in the European Union
In the European Union, several countries (Portugal, Cyprus, Belgium, Poland, Italy and Malta) have in their legislation different ways of calculating national interest deductible from the calculation basis of taxes levied on corporate income (the so-called notional interest deduction – NID).
The standards adopted by countries have different designs, sometimes allowing the calculation of expenses to be deducted based on the total value of the company's net worth accounts (full amount method, as occurs with the JCP), sometimes allowing the calculation to be made based on the increase verified from one year to the next in the net worth accounts (incremental method).
It is possible to cite, as an example, the NIDs provided for in the Belgian and Italian regulations. In Belgium, NIDs were introduced in 2006 and were originally calculated on the total value of asset accounts; subsequently, in a transition, the amount to be deducted began to be calculated based on the incremental value of the adjusted equity accounts.
The interest rate (notional interest rates) varies annually, depending on the interest rates applicable on public debt securities, and there are also objective limits to be observed when setting them.
In Italy, NIDs were introduced in 2011, based on the incremental methodology. Applicable interest rates are also determined annually and set based on state published rates. The variation in net equity cannot be greater than the value of net equity in that year.
NIDs are not identical to JCP. Unlike the JCP, the NID does not presuppose a payment to the partner as a condition for deductibility in the calculation of taxes on corporate income. Its deductibility is made annually based on interest rates published by the tax administration.
Despite the existence of differences in calculation methodology and deduction mechanisms, the fact is that the NID are instruments equivalent to the JCP and their differences arise from issues that involve everything from the greater maturity of each country's tax system to the local macroeconomic reality.
And, considering the growing concern of European countries with the indebtedness of their companies – greatly intensified in Europe following the pandemic –, as well as the fear that the Member States of the European Union would adopt non-uniform NID standards, as a form of government subsidy (state aid), the European Commission presented a directive proposal to establish rules relating to deduction to reduce the debt-equity distortion and the limitation of deductibility of interest in corporate income tax (“DEBRA Directive Proposal”).
The directive proposal has two fundamental components: the first consists of the introduction of an ACE (allowance on corporate equity), whose calculation basis corresponds to the difference between the value of net equity determined at the end of the calculation period (calendar year) and the value of net equity determined at the end of the previous calculation period.
The text defines equity as being the result of the sum of share capital, reserve accounts, including goodwill and revaluation, and accumulated profits or losses, and net equity as corresponding to the difference between the value of the taxpayer's equity and the sum of his shares in the capital of other companies and his own shares.
This adjustment to the value of the equity is intended to ensure that there is no “cascading effect” of the ACE benefit on the corporate group that would otherwise occur if investments related to equity interests (often accounted for using the equity method) were replicated throughout the control chain.
The interest rate is calculated based on a period of ten years, plus a risk-adjusted interest rate that may vary between 1.0% and 1.5%, depending on the characteristics of the taxpayer in question. The European Commission, however, will have the power to change the risk-adjusted interest rate.
Once ACE is granted for a given calendar year, the proposed directive provides for the possibility of deduction, in the year in question, and during the subsequent nine years, totaling ten years. From the European Commission's perspective, the ten-year period would correspond to the average debt maturity period.
Note, however, that, consistent with its incremental systematics, the proposed ACE is subject to a neutralization rule (recapture rule). In the event that the taxpayer reduces the values of their balance sheet accounts, and having already benefited from ACE previously, the amount deducted up until then must be added to the calculation base for taxes on corporate income for a period of ten consecutive years, up to the limit of the benefit granted, in order to neutralize its tax effect.
The proposal also introduced specific anti-avoidance rules designed to prevent taxpayers from using arrangements or businesses to take advantage of the benefits arising from ACE in inappropriate situations. Such rules result in the disregard of additions made to the company's net equity accounts resulting from certain intra-group operations and contributions made originating in jurisdictions without exchange of information.
The purpose of these rules is to avoid operations that lead to the “cascading effect” in which the same ACE expense, resulting from a single asset increase, is deducted multiple times, in several different jurisdictions.
The second component of the European proposal consists of the introduction of a deductibility limitation rule corresponding to 85% of the excessive borrowing costs, that is, the positive difference between expenses and interest income. Therefore, as the company has incurred more expenses than financial income, 15% of the excess amount will be considered completely non-deductible.
As can be seen, although the NIDs adopted by several member countries of the European Union and the European Commission's “DEBRA” Directive Proposal are not identical to the JCP – especially because the former follow an incremental methodology, while the latter has a methodology in which the benefit is granted regardless of the increase verified in the balance sheet accounts – both pursue the same legitimate purpose: limiting the pro-indebtedness bias arising from the income taxation system. income.
From an inductive perspective, Brazilian JCPs have the virtue of not only inducing constant capitalization (after all, the JCP calculation base is increased), but also the maintenance of capital in the company (since JCP deduction is allowed regardless of the increase in equity accounts).
But beyond a theoretical perspective, a recent study conducted by researchers at Fundação Getúlio Vargas (FGV) demonstrates that the adoption of JCPs has grown substantially since 2003. The the aforementioned study concluded that the mechanism was responsible for the reduction in the degree of leverage of publicly traded companies included in the Novo Mercado.
Therefore, the full repeal of the JCP represents a serious setback in fiscal policy, as it deconstructs an important instrument that, by reducing the leverage of Brazilian companies, demonstrably contributes to investment in companies' share capital and, consequently, to the growth of the national economy.
It is interesting to note that the explanatory memorandum accompanying PL 4,258/2023 even recognizes that instruments similar to the JCP are used in other countries. However, instead of considering the possibility of improving the JCP based on the study of international experience, it was decided to revoke it.
Certainly, discussions about improving legal institutes can always be held, and the European experience can be a starting point. But the simple repeal of the JCP, even though it may bring some immediate increase in revenue, is certainly not the most appropriate solution for balancing Brazilian public accounts, as the deleterious effects of its repeal outweigh the potential gains.
For every complex problem, there is always a simple solution – and a wrong one. If PL 4,258/2023 remains as proposed by the federal government, this maxim will, once again, be confirmed.
EDUARDO MANEIRA – Associate Professor of Tax Law at UFRJ. Director of the Brazilian Association of Financial Law – ABDF. Counselor of the OAB/RJ. Member of the CFOAB Special Tax Law Commission. Master in Constitutional Law and PhD in Tax Law from UFMG. Founding partner of Maneira Advogados.
DONOVAN MAZZA LESSA – Partner at Maneira Advogados.
ROBERTO CODORNIZ LEITE PEREIRA – PhD in Tax Law from the Faculty of Law of USP. Master in Law from the São Paulo Law School of Fundação Getulio Vargas. LL.M. in International Tax Law from the Vienna University of Business and Economics (WU). Associate and professor of postgraduate courses at IBDT. Partner of the tax area at Maneira Advogados
See other related news stories





Press
Averages should not ignore the Contumacious Debtor Law, experts say
May 11, 2026Media should not ignore the Contumacious Debtor Law, experts say Risks are greater for companies that fail to comply with balance sheet obligations and are unaware of the situation of related parties By Suzana Liskauskas, Para o Valor — Rio de Janeiro Instituted...
